Canada Revenue Agency
The Canada Revenue Agency (CRA) is the federal body responsible for administering tax laws and delivering benefit programs for the Government of Canada and most provincial and territorial governments. As the largest organization in the federal public service, it collects hundreds of billions in tax revenue annually and administers major social benefits like the Canada Child Benefit. The agency operates under the Minister of National Revenue, currently François-Philippe Champagne, with day-to-day management led by Commissioner Heather Evans. Its work touches nearly every Canadian and business, forming a central part of the country's financial and social framework.
History and evolution
The origins of federal tax collection in Canada date back to the pre-Confederation era when individual colonies managed customs duties. Following Confederation in 1867, Parliament established two separate departments, Inland Revenue and Customs. The financial pressures of the First World War led the Borden government to introduce a personal income tax in 1917, initially as a temporary measure. These two departments were eventually merged into a single entity called Customs and Excise between 1918 and 1927. The Department of National Revenue Act of 1927 formally renamed the department to National Revenue, a title it held for decades as it took on new responsibilities like administering the Canada Pension Plan and the Goods and Services Tax.
In 1999, the Chrétien government transformed the department into the Canada Customs and Revenue Agency (CCRA), aiming to reduce administrative duplication and improve service delivery. This new agency had a broad mandate covering taxation, customs, and border protection. This structure was short lived, as interdepartmental collaboration issues led to the creation of the Canada Border Services Agency in December 2003. Following this spin off, the CCRA was rebranded as the Canada Revenue Agency, focusing exclusively on tax administration and benefit delivery. A significant modernization milestone was the introduction of EFILE for electronic tax submission in 1993.
The CRA's role expanded dramatically during the COVID-19 pandemic. The agency extended filing deadlines for the 2019 tax year and transitioned many staff to remote work. Its most prominent new duty was administering emergency financial benefits, including the Canada Emergency Response Benefit (CERB), processing millions of applications through its systems. According to the agency, nearly 8.5 million Canadians applied for CERB, representing about 21.5 million unique applications before the program closed in December 2020. Looking forward, the agency's 2026-27 Departmental Plan includes an initiative to automatically file taxes for low income Canadians starting with the 2026 tax year, ensuring they receive benefits they qualify for.
Leadership and governance
The Canada Revenue Agency is led politically by the Minister of National Revenue, who is accountable to Parliament and Cabinet for all agency operations. The current minister, François-Philippe Champagne, was appointed on May 13, 2025. The day to day management and chief executive officer function is held by the Commissioner of Revenue, who advises the minister and oversees the agency's vast operations. Heather Evans was appointed to this role on June 23, 2026. The Commissioner is supported by a Deputy Commissioner, currently Jean-François Fortin since May 6, 2024, who acts in the Commissioner's absence and handles specific assignments.
A 15 member Board of Management provides strategic oversight. Eleven members are appointed by provincial and territorial governments, two by the federal government, and the Commissioner serves as an ex officio member. Board members typically serve three year terms. The board's primary role is to oversee the development of the CRA's annual Corporate Business Plan, which sets objectives and financial allocations. It is divided into several committees focusing on audit, governance, human resources, and service transformation. The board does not engage in business operations, enforce legislation, or have access to taxpayer information.
The Canada Revenue Agency maintains four advisory committees to assist it in operational planning and decision-making. These advisory committees consist of tax professionals, lawyers, accountants, and community leaders that help the agency improve its service delivery within a specific area. The current advisory committees are the Advisory Committee on the Charitable Sector, the Audit File Resolution Committee, the Disability Advisory Committee, and the Offshore Compliance Advisory Committee. These committees provide valuable feedback to the agency from external experts.
Organizational structure
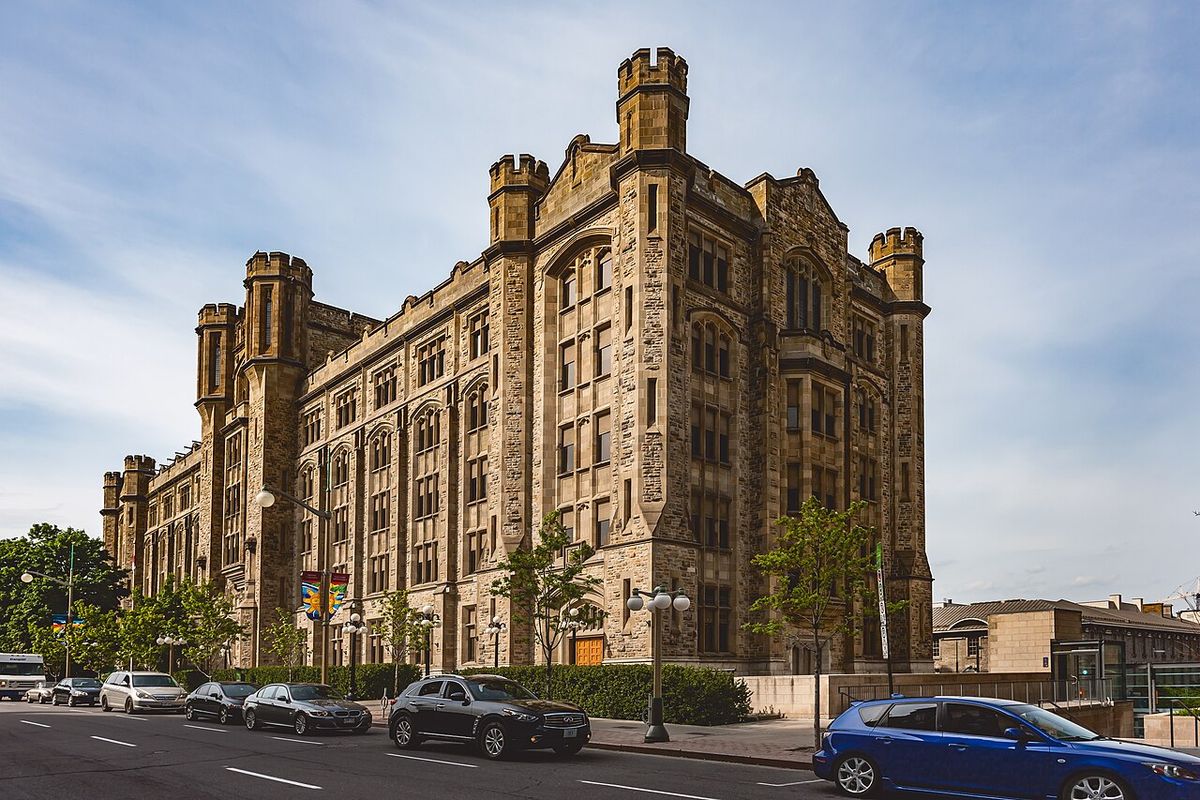
The CRA's headquarters in Ottawa houses the central functions for ministerial reporting, corporate planning, human resources, information technology, and the interpretation of tax legislation. This central office is divided into five program branches that deliver the core tax and benefits mandate and seven corporate branches that provide internal support services. Beyond Ottawa, the agency's nationwide operations are organized into four geographic regions: Atlantic, Ontario, Quebec, and Western. Each region is headed by an Assistant Commissioner who oversees local tax centres and offices.
The physical processing of tax returns is handled by four specialized Tax Centres located across the country, each assigned specific geographic areas. The Jonquière Tax Centre serves Quebec, the Prince Edward Island Tax Centre serves the Atlantic region, the Sudbury Tax Centre serves Ontario, and the Winnipeg Tax Centre serves the Prairie and Pacific areas. For more complex audit and collection cases requiring direct taxpayer interaction, the agency operates 25 Tax Services Offices (TSOs) located in every province. The territories do not have standalone TSOs but are served by offices in other regions.
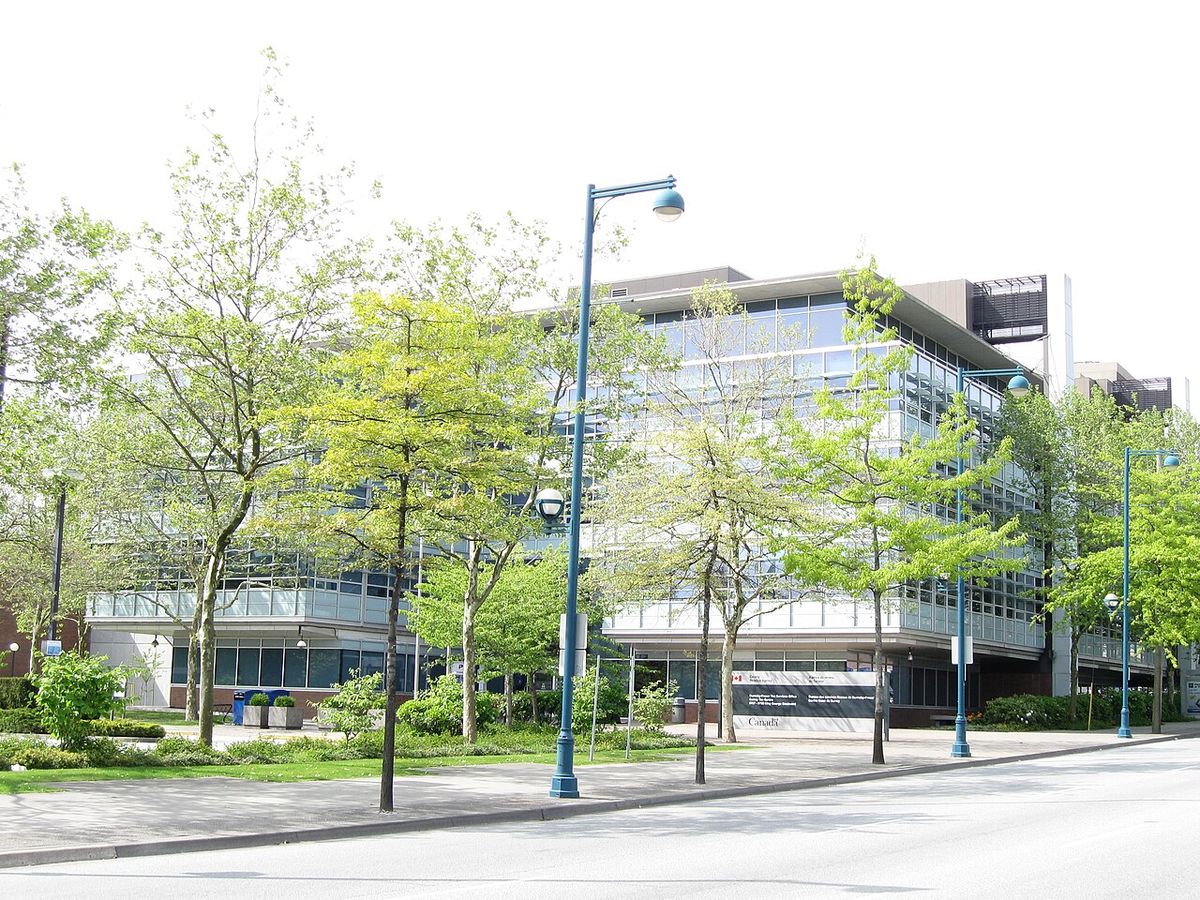
The CRA introduced National Verifications and Collections Centres in 2016 as part of an effort to modernize the Agency's services. These centres are responsible for non-complex files related to collection, verification, and validation that do not involve in-person interaction. There are three NVCCs located across Canada in St. John's, Shawinigan, and Surrey. In 2019, the CRA introduced Northern Service Centres to provide access to tax services and assistance for residents in the Yukon, Northwest Territories, and Nunavut. These three centres are co-located with existing Service Canada offices in Whitehorse, Yellowknife, and Iqaluit.
Core operations: tax collection
The CRA's primary function is the collection of taxes on behalf of the federal government and most provincial and territorial governments, with Quebec being the notable exception. This includes personal and corporate income taxes, the Goods and Services Tax, Harmonized Sales Tax, various excise duties, and fuel charges. The agency enforces compliance through audits, examinations, and collections activities, applying penalties when necessary. As a separate agency, it maintains cost recovery agreements with provinces to administer non harmonized sales tax programs.
For personal income tax, Canada uses a bracketed system with rates set by the Department of Finance. Taxes are levied by both federal and provincial governments but are collected together by the CRA, except in Quebec where residents must file separately with Revenu Québec. Employers typically deduct income tax, Canada Pension Plan or Quebec Pension Plan contributions, and Employment Insurance premiums from employee paycheques. Self employed individuals and those with investment income must remit payments directly, often in quarterly instalments.
The agency also administers corporate income taxes for most provinces, except Alberta and Quebec. Ontario transferred this responsibility to the CRA in 2008. Provinces maintain dual corporate tax rates, with a lower rate for income qualifying for the federal small business deduction. The federal Goods and Services Tax is a value added tax of 5 percent, collected by the CRA in all provinces. In Quebec, Revenu Québec administers the GST for businesses alongside the Quebec Sales Tax. The Harmonized Sales Tax, which combines the federal GST with a provincial sales tax, is administered by the CRA in Prince Edward Island, New Brunswick, Newfoundland and Labrador, Nova Scotia, and Ontario.
Benefits and credits delivery
In addition to tax collection, the CRA delivers a wide array of social benefits and tax credits, acting as a key distributor of federal and provincial social policy. These programs are largely income tested, meaning eligibility and payment amounts are based on household income as reported in annual tax returns. This link between filing taxes and receiving benefits shows the agency's central role in the social safety net. Major federal benefits include the Canada Child Benefit, the Climate Action Incentive, and the Disability Tax Credit.
The Canada Child Benefit (CCB), introduced in July 2016, is a non taxable monthly payment to assist families with the cost of raising children under 17. The benefit amount is calculated based on adjusted family net income, requiring families to file their taxes annually to be assessed. The CCB consolidated and replaced previous child benefit programs like the Universal Child Care Benefit and the Canada Child Tax Benefit. During the COVID-19 pandemic, the CRA's role expanded to administer emergency economic measures, most notably the Canada Emergency Response Benefit (CERB). This taxable benefit provided $2,000 per month to eligible workers who lost income due to the pandemic, with the CRA processing millions of applications.
The agency also administers incentive programs that function like business grants, primarily through refundable tax credits. The largest of these is the Scientific Research and Experimental Development (SR&ED) program, which provides over $3 billion annually to more than 20,000 Canadian businesses to encourage innovation. According to a 2024 Access to Information release, the CRA applied gross negligence penalties to SR&ED claimants in multiple years between 2018 and 2024, with annual penalty amounts between $0 and approximately $5.2 million. Other targeted incentives support film and media production, clean technology, and regional development. These programs are designed to lower the tax burden for businesses and effectively provide funding to fuel economic growth and job creation.
Financial and operational data
The Canada Revenue Agency is the largest employer in the federal public service, with 54,933 personnel and an operating budget of $5.1 billion as of the 2018-19 fiscal year. Despite its headquarters being in Ottawa, only about 12,000 employees work in the National Capital Region. The workforce composition from that period included 32,598 permanent employees, 10,057 contract employees, and 1,251 students, with an average employee age of 45. As a separate agency under Schedule V of the Financial Administration Act, the CRA has flexibility in human resources, allowing it to set its own job classifications and pay rates, and negotiate labour contracts independently.
The majority of CRA employees are represented by the Union of Taxation Employees, a component of the Public Service Alliance of Canada. Auditors, investigators, and computer systems employees are represented by the Professional Institute of the Public Service of Canada, while executives, management, and students are generally not unionized. The agency's prescribed interest rate, used for calculating taxable benefits on low interest loans, remained steady at 3 percent for the fourth quarter of 2026, marking the sixth consecutive quarter at that rate. This rate is based on the three month average of Government of Canada Treasury bill yields.
The scale of the CRA's financial operations is immense. During the 2017 tax year, it collected approximately $430 billion in revenue for federal and provincial governments. In the same period, it administered nearly $34 billion in benefits to Canadians. More recent figures from the Fiscal Monitor show revenues in June 2026 totalled $44.8 billion, though tax revenues specifically decreased by 4.1 percent compared to June 2025. The Spring Economic Update 2026 proposed providing $18.7 million over three years, starting in 2026-27, to renew certain CRA initiatives.
Key dates and milestones
The evolution of Canada's revenue service is marked by several legislative and operational milestones that have shaped its current form and function. These events highlight the agency's shift from a traditional government department to a modern, service oriented organization with an expanding role in both revenue collection and social program delivery. The timeline includes the establishment of foundational departments after Confederation and the introduction of income tax during the First World War. It also covers the technological shift with electronic filing and the structural changes that created the modern CRA and its sister border agency. The following list details these key moments in chronological order.
- 1867: Establishment of separate Inland Revenue and Customs departments after Confederation.
- 1917: Introduction of the federal personal income tax as a temporary wartime measure.
- 1927: Enactment of the Department of National Revenue Act, renaming Customs and Excise to National Revenue.
- 1993: Launch of EFILE, allowing for electronic tax return submission.
- 1999: Transformation of Revenue Canada into the Canada Customs and Revenue Agency (CCRA).
- December 2003: Creation of the Canada Border Services Agency from the CCRA, leading to the rebranding as the Canada Revenue Agency.
- July 2016: Implementation of the Canada Child Benefit, replacing previous child benefit programs.
- 2026: Plan to begin automatically filing taxes for low income Canadians for the 2026 tax year.
Major tax and benefit programs administered
The CRA administers a complex portfolio of programs that directly impact government revenue and individual financial well being. The following table outlines some of the key taxes collected and benefits delivered, illustrating the agency's broad scope. This portfolio demonstrates how the CRA's operations extend far beyond simple tax collection to include significant wealth redistribution and economic stimulus functions. The administration of these programs requires a massive technological and human resource infrastructure, from processing basic returns at tax centres to conducting complex audits at field offices. The table categorizes programs by type and provides a brief description of their primary function and key administrative details.
| Program Type | Name | Key Detail |
|---|---|---|
| Tax | Personal Income Tax | Collected for all provinces except Quebec. Uses a bracketed rate system. |
| Tax | Corporate Income Tax | Administered for most provinces, except Alberta and Quebec. Features dual provincial rates. |
| Tax | Goods and Services Tax (GST) | Federal value added tax of 5%. Administered by Revenu Québec for businesses in Quebec. |
| Tax | Harmonized Sales Tax (HST) | Combined federal-provincial sales tax in PEI, NB, NL, NS, and ON. Administered by CRA. |
| Benefit | Canada Child Benefit (CCB) | Non-taxable, income-tested monthly payment for families with children under 17. |
| Benefit | GST/HST Credit | Tax-free quarterly payment to help low- and modest-income individuals and families offset sales taxes paid. |
| Benefit | Disability Tax Credit (DTC) | Non-refundable tax credit to reduce income tax for persons with disabilities or their supporting persons. |
| Business Incentive | Scientific Research & Experimental Development (SR&ED) | Tax incentive program providing over $3 billion annually to support business R&D. |
Questions about Canada Revenue Agency
What is the Canada Revenue Agency (CRA) responsible for?
The Canada Revenue Agency is responsible for administering most federal, provincial, and territorial tax laws in Canada. This includes collecting personal and corporate income taxes, the Goods and Services Tax, and Harmonized Sales Tax. Beyond taxation, the CRA delivers major social benefit programs like the Canada Child Benefit and the GST/HST Credit. It also oversees the registration of charities and administers business incentive programs such as the Scientific Research and Experimental Development tax credit.
Who is the current Minister of National Revenue?
The current Minister of National Revenue is François-Philippe Champagne. He was appointed to the position on May 13, 2025. The Minister is accountable to Parliament and Cabinet for all of the CRA's operations and matters related to tax and benefit administration in Canada. The Minister provides political leadership and direction for the agency.
What is the difference between the CRA and Revenu Québec?
The CRA administers tax laws and collects taxes for the federal government and for all provinces and territories except Quebec. Revenu Québec is the provincial revenue agency responsible for administering Quebec's own tax laws. Quebec residents must file a separate provincial income tax return with Revenu Québec, while filing their federal return with the CRA. Revenu Québec also administers the Goods and Services Tax for businesses operating in Quebec, alongside the Quebec Sales Tax.
What benefits does the CRA administer?
The Canada Revenue Agency administers income-tested benefits and credits on behalf of the Government of Canada and most provinces and territories. Key federal programs include the Canada Child Benefit, which assists families with children under 17, and the GST/HST Credit. The agency also delivers the Climate Action Incentive and the Disability Tax Credit. During the COVID-19 pandemic, the CRA was tasked with delivering emergency benefits like the Canada Emergency Response Benefit and the Canada Emergency Student Benefit.
How can businesses get funding or tax credits from the CRA?
The CRA administers several tax incentive programs that function like funding for businesses. The largest is the Scientific Research and Experimental Development program, which provides tax credits for eligible research and development activities. Other incentives exist for film and media production, clean technology, and regional development. These are typically refundable or non refundable tax credits that reduce a company's tax payable or result in a cash refund, effectively providing financial support for specific business activities.
What is the CRA's prescribed interest rate for 2026?
The Canada Revenue Agency's prescribed interest rate remained at 3 percent for the fourth quarter of 2026, from October 1 to December 31. This was the sixth consecutive quarter the rate held at this level. This rate is used to calculate taxable benefits for employees and shareholders who receive interest free or low interest loans. It is based on the three month average of Government of Canada Treasury bill yields and is set quarterly.
Sources and further reading
- Canada Revenue Agency (Wikipedia)
- Canada Revenue Agency (CRA) Funding Programs | 2026 (hellodarwin.com)
- Canada Revenue Agency prescribed rate unchanged for ... (krp.ca)
Checked by the Nosy Mag desk. Last updated 2026-10-29.