Canada Savings Bond
The Canada Savings Bond was an investment instrument offered by the Government of Canada from 1945 to 2017. It was issued by the Bank of Canada and sold annually between early October and December 1. The bonds offered a competitive interest rate with a guaranteed minimum, providing a low-risk, guaranteed investment redeemable at most financial institutions. The program was inspired by the Victory Bonds of the World Wars. Its popularity declined in later decades due to high administrative costs and more attractive investment alternatives, leading to its discontinuation announced in the 2017 federal budget.
Historical origins and evolution
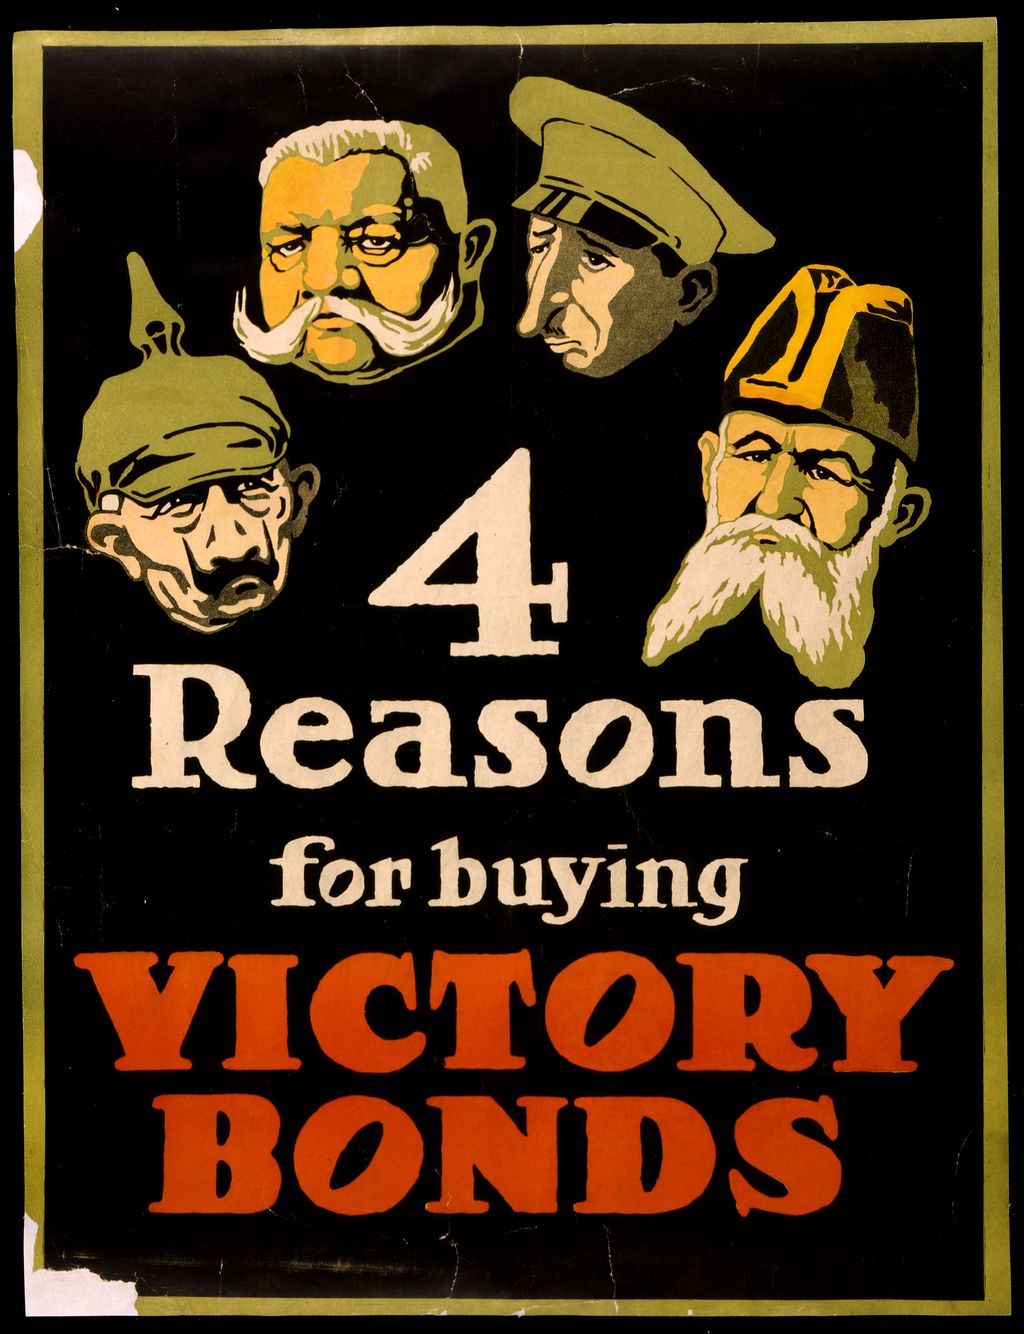
The Canada Savings Bond program has its roots in the Victory Bond campaigns of the First and Second World Wars. The government first sold war bonds, marketed as Victory Bonds, beginning in 1917 to fund the Allied war effort. These campaigns utilized extensive publicity, including artwork, parades, and celebrity endorsements. The success of these wartime instruments demonstrated the public's willingness to lend directly to the government, a model revived for World War II.
In 1945, the government launched the Canada Savings Bond program to replicate this success for peacetime financing. By 1987, the total value of CSBs issued stood at approximately $55 billion. However, the following decades saw a steep and consistent decline in issuance. A 2004 report commissioned by the Department of Finance recommended scrapping the program to save an estimated $650 million over nine years.
Then finance minister Ralph Goodale rejected the idea, citing the program's popularity, especially with first-time investors. Instead, changes were made to make the bonds more competitive. The value of bonds issued declined from $55 billion in 1987 to just over $6 billion in 2015. A government-commissioned study by KPMG in June 2015 again recommended cancellation, noting the program cost taxpayers an estimated $58 million annually.
The Department of Finance initially ruled out cancellation. However, by October 2016, the newly elected Liberal government was considering ending the program. The final decision was announced in the federal budget on March 22, 2017. The budget stated the sale of new CSBs would be discontinued that year, with no further purchases permitted after November 2017.
Bond types and key features
The core product was the Canada Savings Bond, which was available in two interest payment styles. Regular interest bonds paid interest directly to the bondholder, typically by cheque or direct deposit on each anniversary of the issue date. Compound interest bonds added the accrued interest to the principal each year, with the entire sum paid out only upon redemption or maturity. The interest rate for a standard CSB was guaranteed for the first year and could fluctuate with market conditions for the remaining nine years of its term.
These bonds were redeemable at any time at most financial institutions. In 1997, the government introduced the Canada Premium Bond as a complementary product. These bonds also came in regular and compound interest varieties but offered a key difference in rate stability. The interest rate for a Canada Premium Bond was fixed for the first three years, after which it could fluctuate for the remaining seven years until maturity.
This greater stability was considered a premium feature. In exchange, CPBs were only redeemable on the anniversary of their issue date or during the 30 days immediately following. A third product was the Canada Investment Bond, introduced in 2003. These were non-redeemable, shorter-term bonds with a three-year maturity, available exclusively through investment brokers.
Only six series were issued before the product was discontinued in 2004. All CSBs and CPBs had a final maturity date. The program administrator confirmed that all bonds had matured and stopped earning interest as of December 2021. This marked the definitive end of the program's financial obligations.
- Canada Savings Bond (CSB): Redeemable anytime. Rate guaranteed for 1 year.
- Canada Premium Bond (CPB): Redeemable only on anniversary date + 30 days. Rate fixed for 3 years.
- Canada Investment Bond: Non-redeemable. 3-year term. Broker-sold only.
- Regular Interest: Interest paid out periodically to the holder.
- Compound Interest: Interest reinvested into principal until redemption.
Purchase and redemption process
Canadians could purchase Canada Savings Bonds through several channels, with the payroll savings program being a common method. Many employers allowed employees to authorize automatic deductions from their pay to purchase bonds. Bonds could also be bought directly from most financial institutions, including banks and credit unions. Investment brokers were another channel, particularly for products like Canada Investment Bonds.
The annual sales campaign ran from early October until December 1. This widespread availability made CSBs a familiar and accessible financial product for generations. Redeeming bonds was designed to be straightforward for certificate holders. Physical, certificated bonds could be cashed at most financial institutions in Canada at any time for CSBs.
For Canada Premium Bonds, redemption was only permitted during the annual redemption window. Owners could also use an automated telephone service or the dedicated Canada Savings Bonds online service. For bonds held within the payroll savings plan, the proceeds were typically paid out by cheque or direct deposit upon maturity. This system ensured that even after the program ended, investors could access their funds.
In cases where a physical bond was lost, stolen, or destroyed, the process for recovery and redemption remained in place. Owners needed to report the loss by calling the Canada Savings Bonds program. To facilitate the process, they were advised to have relevant information on hand, such as the bond serial number and issue date. The government guaranteed the value of all issued bonds, protecting investors even if the physical certificate was missing.
Decline and discontinuation
The decline of the Canada Savings Bond program was the result of converging financial and economic factors. Financially, the government found it could raise funds more efficiently by issuing bonds directly to large financial institutions. The administrative burden became difficult to justify as issuance shrank. The KPMG study in 2015 quantified this burden, estimating the program's direct cost to taxpayers at $58 million per year.
This high cost for a declining product was a primary factor in the decision to end the program. From an investor's perspective, the appeal of CSBs waned as new investment vehicles entered the mainstream market. The rise of mutual funds, exchange-traded funds, and high-interest savings accounts offered the potential for higher returns. Persistently low interest rates in the 2010s meant CSB yields often fell below the rate of inflation.
The guaranteed minimum interest rate at the time of discontinuation was 0.5 percent. The government cited the availability of numerous other savings options for Canadians and the high cost of maintaining the program as the primary reasons for its termination. While no new bonds could be purchased after November 2017, the government affirmed that all existing bonds would continue to be honoured. They would be honoured until redeemed or until they reached their final maturity date, which for all bonds was December 2021.
This ensured that no investor would lose their principal due to the program's end. The final maturity meant all bonds stopped earning interest after that date. The closure of the program marked the end of a significant chapter in Canadian retail finance. It reflected broader shifts in how both governments raise money and how citizens choose to save.
Provincial counterparts and alternatives
The success of the federal Canada Savings Bond program inspired several provinces to create their own retail debt instruments for residents. Ontario launched the Ontario Savings Bond in 1995, offering variable rate, step-up, and fixed-rate bonds exclusively to Ontario residents. That program ended in 2018. Quebec established Épargne Placements Québec, which issued Quebec Savings Bonds.
Similarly, Saskatchewan offered Saskatchewan Savings Bonds to its residents. These programs operated on similar principles, providing a local government funding source and a guaranteed investment option for provincial citizens. For Canadians seeking low-risk investments after the end of the CSB program, several alternatives exist. Guaranteed Investment Certificates are among the most direct comparisons.
GICs offer a fixed term and a guaranteed return, with principal protection up to certain limits through the Canada Deposit Insurance Corporation. GICs come in various forms, including cashable and fixed-term products. Another alternative is federal or provincial Treasury Bills, which are short-term government debt securities purchased at a discount and redeemed at face value. These typically require a higher minimum investment and are bought through brokers.
Other common savings vehicles include high-interest savings accounts, which provide liquidity and a better return than standard savings accounts. For those with a higher risk tolerance, mutual funds and exchange-traded funds offer exposure to equity and bond markets with the potential for greater growth. Registered accounts like Tax-Free Savings Accounts and Registered Retirement Savings Plans can be used to hold many of these alternatives. This provides tax advantages that CSBs also offered when held within such shelters.
| Investment Alternative | Key Feature | Risk Profile |
|---|---|---|
| Guaranteed Investment Certificate (GIC) | Fixed term, guaranteed return, CDIC insured | Low |
| Treasury Bill (T-Bill) | Short-term government debt, purchased at discount | Low |
| High-Interest Savings Account (HISA) | Liquid, interest-earning | Low |
| Mutual Fund / ETF | Market exposure, professional management | Medium to High |
Tax treatment and registered plans
Interest earned on Canada Savings Bonds held outside of a registered tax shelter was fully taxable as income in the year it was received. For regular interest bonds, this meant taxpayers declared the interest payments each year on their annual tax return. For compound interest bonds, the entire accrued interest was taxable in the year the bond was redeemed. This could result in a significant tax liability if a bond had been held for many years.
The tax rate applied depended on the bondholder's marginal income tax rate. This was an important consideration for investors planning their cash flow and tax obligations. A key feature of CSBs and CPBs was their eligibility to be held within registered retirement and savings plans. These plans provided significant tax advantages for Canadian investors.
Canadians could purchase bonds within a Registered Retirement Savings Plan, where contributions were tax-deductible and investment growth was tax-deferred until withdrawal. Bonds could also be held in a Tax-Free Savings Account, where contributions were made with after-tax dollars but all interest earned and withdrawals were completely tax-free. This flexibility allowed investors to use the guaranteed returns of government bonds as a conservative component within their broader retirement or savings strategy. It helped optimize their after-tax returns.
For individuals who held a Canada RSP or Canada RIF, which were registered plans administered directly by the Canada Savings Bond program, special steps were required after the program wound down. These plans stopped earning interest when the bonds within them matured. Owners were required to transfer the funds to another registered account at a financial institution or contact the CSB program to withdraw the money. Any withdrawal from these plans counted as taxable income in the year it was received.
Questions about Canada Savings Bond
Can I still cash in my old Canada Savings Bonds?
Yes, you can still redeem Canada Savings Bonds that were issued before the program ended. Although no new bonds have been sold since November 2017 and all bonds stopped earning interest after December 2021, the Government of Canada guarantees the value of all issued bonds. You can cash certificated bonds at most financial institutions in Canada. If your bonds were part of a payroll savings plan, the proceeds would have been sent to you upon maturity.
What is the difference between a Canada Savings Bond and a Canada Premium Bond?
The main differences concern interest rate stability and redemption rules. A Canada Savings Bond had an interest rate guaranteed for the first year only and was redeemable at any time. A Canada Premium Bond, introduced in 1997, offered an interest rate fixed for the first three years. In exchange, a CPB could only be redeemed on the anniversary of its issue date or during the 30 days immediately following that date.
Why did the government stop selling Canada Savings Bonds?
The federal government discontinued the program due to high costs and declining popularity. A 2015 study estimated the program cost taxpayers $58 million annually to administer, while the total value of new bonds issued had plummeted from $55 billion in 1987 to just over $6 billion in 2015. Simultaneously, Canadians gained access to a wider array of investment options. The 2017 federal budget concluded the program was no longer a cost-effective way for the government to raise funds.
What should I do if I lost my physical bond certificate?
If your Canada Savings Bond or Canada Premium Bond certificate is lost, stolen, or destroyed, you can still redeem it. You need to report the bond as lost by calling the Canada Savings Bonds program. Have any information you possess about the bond ready, such as the serial number and issue date. The government guarantees the value of issued bonds, and the program administrator has a process to verify ownership and issue payment for lost certificates.
Are Canada Savings Bonds taxable?
Yes, interest earned on Canada Savings Bonds is taxable. For regular interest bonds, the interest paid out each year must be declared as income. For compound interest bonds, the total accrued interest is taxable in the year you redeem the bond. The interest is taxed at your marginal income tax rate. However, you could purchase CSBs within registered plans like an RRSP or TFSA, where the interest would grow tax-deferred or tax-free.
What are some good alternatives to Canada Savings Bonds today?
Common low-risk alternatives include Guaranteed Investment Certificates, which offer a fixed term and a guaranteed return with CDIC insurance. Treasury Bills are short-term government debt securities purchased at a discount. High-interest savings accounts provide liquidity and a better return. For those seeking potential growth with higher risk, mutual funds and exchange-traded funds are widely available. Many of these alternatives can also be held within registered accounts like TFSAs and RRSPs for tax advantages.
Sources and further reading
- Canada Savings Bond (Wikipedia)
- Canada Savings Bonds: What you Need to Know (nbc.ca)
- What Will Replace Canada Savings Bonds? (springfinancial.ca)
- Canada Savings Bonds (wowa.ca)
Checked by the Nosy Mag desk. Last updated 2026-10-31.